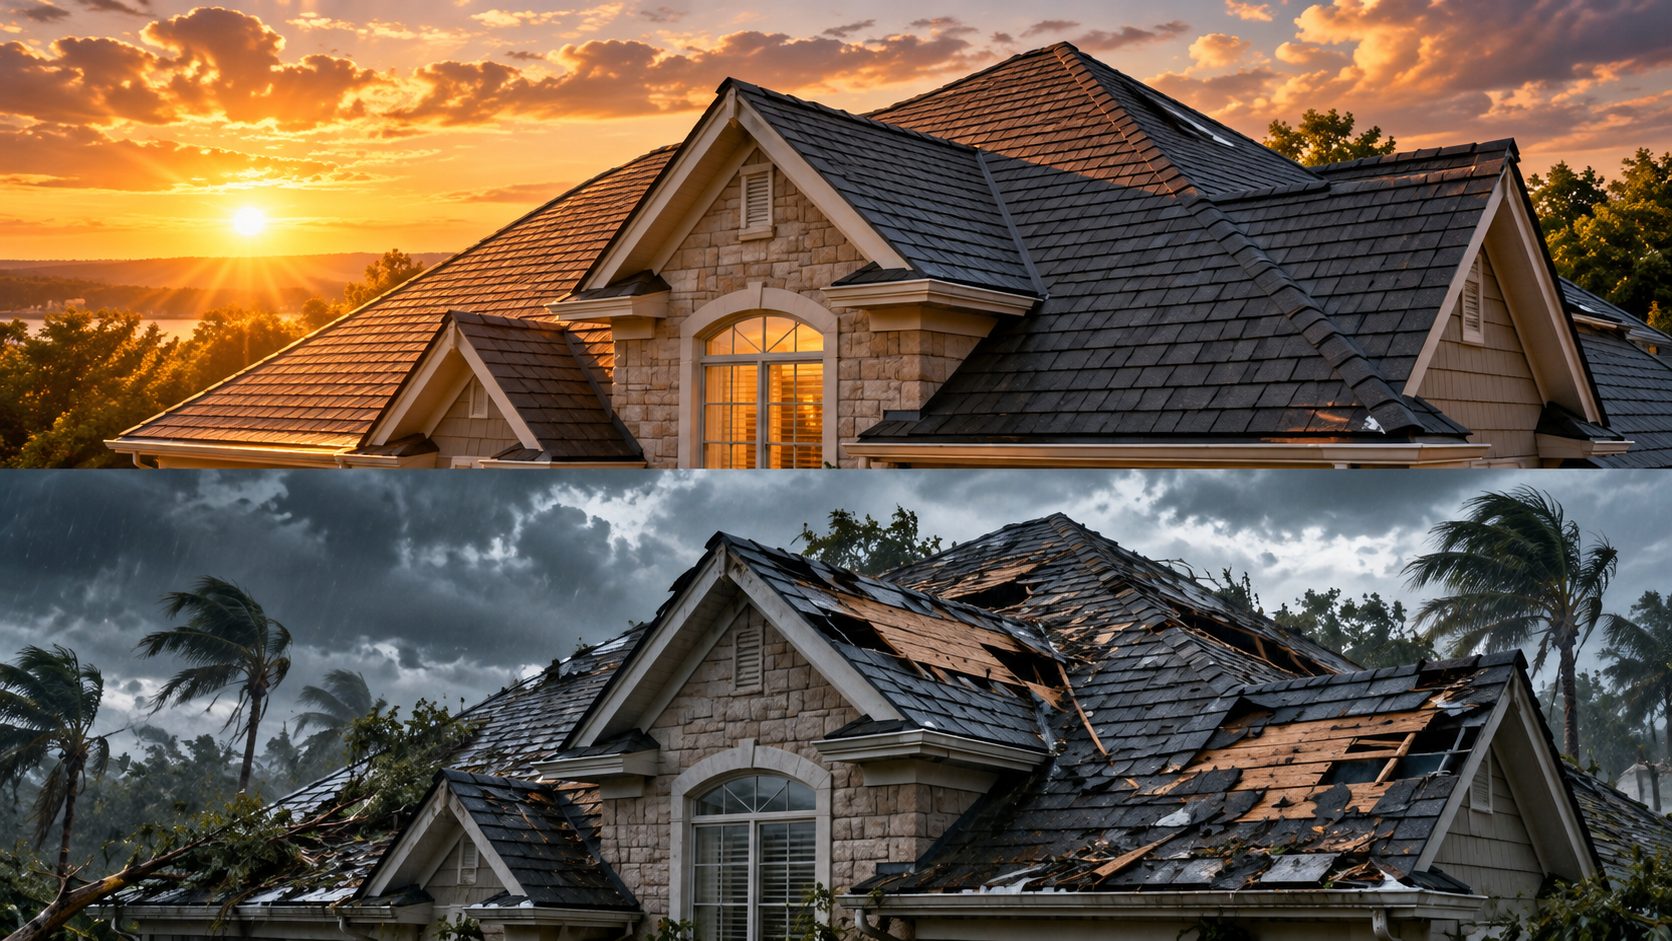
The short answer: a storm damage claim is won or lost in the first 72 hours. Photograph everything before you clean up, make temporary repairs to prevent further damage (keep every receipt), get a licensed roofer's inspection before the adjuster arrives, and file promptly — Florida allows one year from the date of loss, but waiting weakens your evidence. Hurricane deductibles in Florida are usually 2% of your dwelling coverage. Never sign away your claim rights and never accept a deductible "waiver" — that's fraud.
Step 1: Document Before You Clean Up
Your first instinct after a storm is to clear debris — resist it until the damage is recorded. Photos taken after cleanup are far weaker evidence. Walk your property and photograph:
- Every elevation of the roof, from the ground, including downed shingles and flashing in the yard
- Wide shots showing the whole roof, then close-ups of every damaged area
- Interior damage — ceiling stains, wet insulation, dripping areas — with a ruler or coin for scale
- The date-stamped weather report for your address (a screenshot of the storm track works)
Video walkthroughs with narration ("it's October 9th, this is the west slope…") are even better. This documentation is the foundation of everything that follows.
Step 2: Mitigate — Your Policy Requires It
Every homeowner policy includes a duty to mitigate: you must take reasonable steps to prevent further damage. For a roof, that means an emergency tarp over openings, boarded skylights, and buckets under active leaks. Keep every receipt — tarping, temporary materials, even hotel stays if the home is uninhabitable. Reasonable mitigation costs are typically reimbursable as part of a covered claim. What you must not do is permanent repairs before the adjuster's inspection — replacing the roof before the carrier documents the damage can void the claim.
Step 3: Get an Independent Roof Inspection — Before the Adjuster
The insurance company's adjuster works for the insurance company. Having your own licensed roofing contractor inspect first changes the dynamic entirely: you arrive at the adjuster meeting with dated photographs, measurements, and a written scope of damage that the adjuster has to respond to line by line. Our storm inspections are free, take about an hour, and produce exactly the photo documentation packet insurers ask for. If the damage is clearly below your deductible, we'll tell you that too — filing a claim that nets zero can still count against your claims history.
Step 4: Know Your Deadlines
| Florida | Alabama | |
|---|---|---|
| Deadline to file a new claim | 1 year from date of loss (state law) | Set by your policy — most require "prompt notice"; many use 1-year reporting windows |
| Supplemental claims | 18 months from date of loss | Governed by policy terms |
| Hurricane deductible | Usually 2% (sometimes 5%) of dwelling coverage; when it applies, no other deductible can be charged on the same loss | Wind/hail deductibles vary by policy; coastal policies often carry percentage deductibles |
| Lawsuit window (if disputed) | Governed by current statutes — consult a licensed attorney | Breach-of-contract claims generally up to 6 years; bad-faith claims generally 2 years |
Deadlines sound generous. They are not a reason to wait: evidence degrades, damage spreads, and carriers question late claims harder. File within days, not months.
Step 5: Understand What Your Policy Actually Pays
Two policies that look identical on the declarations page can pay wildly differently:
- Replacement Cost Value (RCV) pays what a new roof actually costs, minus your deductible. Depreciation is usually paid out after you complete the work — submit your final invoice to recover it.
- Actual Cash Value (ACV) subtracts depreciation first. On a 15-year-old shingle roof, ACV can mean recovering a fraction of replacement cost.
- Wind-driven rain vs. flood: water that enters through a wind-created opening is typically covered by your homeowner's policy; rising water and storm surge are only covered by a separate flood policy. Insurers sometimes blur this line — your roofer's photos of the opening in the roof are what settles it.
Step 6: Meet the Adjuster With Your Roofer Present
Schedule the adjuster visit and ask your roofing contractor to be there. Two sets of eyes on the roof means damage doesn't get "missed," and measurements get agreed on the spot instead of disputed for months. A contractor can document and scope — but note that in Florida, contractors cannot legally negotiate or adjust your claim; that's reserved for licensed public adjusters and attorneys. If your claim is underpaid or denied, that is when you bring in a public adjuster or attorney, and your contractor's documentation becomes their ammunition.
The Mistakes That Get Claims Denied
- Cleaning up before documenting. No photos, no proof.
- Permanent repairs before the adjuster visit. Tarp yes, re-shingle no.
- Signing an Assignment of Benefits (AOB) or any contract that transfers your claim rights. Florida has heavily restricted AOBs for a reason — read anything you're asked to sign.
- Accepting a deductible "waiver." It's insurance fraud, full stop — for the contractor and for you.
- Waiting. Six months of rain through a small breach turns a covered repair into an excluded "neglect" problem.
- Letting storm chasers on your roof. Out-of-state crews flood the Gulf Coast after every named storm. Verify licenses — Florida licenses at MyFloridaLicense.com — and never pay in full upfront.
If Your Claim Is Denied or Underpaid
A denial is not the end. Request the adjuster's report in writing, submit a supplemental claim with your contractor's independent scope and photos, invoke your policy's appraisal clause (each side hires an appraiser; a neutral umpire breaks ties), or file a complaint with your state's insurance department — the Florida Department of Financial Services or the Alabama Department of Insurance. Many denials are reversed once better documentation is on the table.
Start With a Free Storm Inspection
If a storm has hit your home in the Pensacola–Mobile corridor, call us before you call your insurer. We'll document the damage properly, tarp what needs tarping, and give you an honest read on whether a claim makes sense. This guide is general information, not legal advice — for disputed claims, consult a licensed attorney or public adjuster.
Get an Exact Number for Your Roof
Online ranges are a starting point. A free on-roof inspection with a written, itemized quote takes the guesswork out — no obligation, no pressure.